Our markets and operating environment
We summarise key issues and trends in our operating environment for further insight on our performance.
 |
|
Global growth
- Relatively steady growth as key global economies recover - reflecting rising employment and benign inflation
| Ave % y/y |
2015a |
2016a |
2017f |
2018f |
| US |
2,6 |
1,6 |
2,0 |
2,0 |
| Eurozone |
2,0 |
1,6 |
1,9 |
1,7 |
| Japan |
1,2 |
1,0 |
1,5 |
1,0 |
| China |
6,9 |
6,7 |
6,5 |
6,3 |
| South Africa |
1,3 |
0,3 |
0,7 |
1,1 |
|
|
a Actual f Forecast
South African economy
- South Africa out of sync with global recovery, and
briefly slipped into recession in 2017
(first time
since 2009)
- SA current business cycle downswing has lasted
four years, marking the second-longest downturn in
its history
- Fiscus under extreme pressure: lower tax collections
(estimate – R51 billion), higher contingent liabilities
from treasury guarantees on borrowings by
state-owned entities (R689 billion), sovereign credit
rating downgrades (with further downgrades likely)
|
| |
|
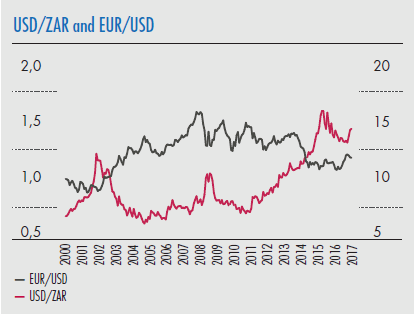 - Despite broadly strengthening in 2017, rand extremely vulnerable to negative domestic political and economic news
- Inflation of 6,3% vs 0,2% real growth in personal income in 2016 keeping household expenditure under extreme pressure
|
|
- Overall consumer spending environment expected to remain weak over the near term (weaker exchange rate, higher taxes + fuel levies (some R25 billion from consumers’ pockets), higher fuel price (at 2014 peaks)
|
|
| Long-term trends in real income per person since 2011 |
|
|
%
2011 - 2016 |
|
| |
R0 - R12 700 |
22,7 |
|
| |
R12 701 - R51 000 |
6,0 |
|
| |
R51 001 - R111 000 |
(1,9) |
|
| |
R111 001 - R240 000 |
(4,9) |
|
| |
R240 001 - R382 000 |
(6,8) |
|
| |
R382 001 - R787 000 |
(15,4) |
|
| |
R787 001 - R1 698 000 |
(19,7) |
|
| |
R1 698 001 + |
(30,6) |
|
| |
Average |
0,4 |
|
| |
Source: BMR, Standard Bank Research. |
|
|
| |
|
|
|
|
- Unemployment reaches highest level in over a decade
|
|
Political climate
- Knock-on effects of political uncertainty evident
across economic sectors
- Significant economic risk from political developments
ahead of ANC elective conference in December
2017 and run-up to 2019 elections
|
|
Retail sector
- Slowdown in consumer spending has significant
impact on JSE-listed consumer goods companies
- Year-on-year food price inflation at two-year low of
5,7% in August after averaging 8,4% in the first half.
Forecast of 3,2% by early 2018
- Deflation in key raw material prices
|
Key commodity price changes
|
End-September |
% y/y |
| Brent crude (US$/bb) |
57,0 |
21,6 |
| US wheat (US cents/bu) |
461,5 |
(3,5) |
| SA white maize (R/t) |
1 830 |
(49,0) |
| SA yellow maize (R/t) |
1 953 |
(35,4) |
| SA wheat (R/t) |
4 063 |
(3,3) |
- Record maize crop estimated at over 16 million
metric tonnes in the 2017 season more than double
a year earlier, when the worst drought in over a
century reduced the harvest to a nine-year low
Source: StatsSA, SARB, economic reports.
