
Governance review
Remuneration report
Mark Bowman, Chairman
SECTION 1: BACKGROUND
Statement from the chairman of the remuneration committee
Dear Stakeholder
On behalf of the remuneration committee, I am pleased to present the 2018 summarised remuneration report, which highlights:
- Key components of our remuneration policy
- Alignment of these components with the Tiger Brands business strategy
- Implementation of the policy for the 2018 financial year (FY18).
The remuneration report
In line with our commitment to comply with King IV, our remuneration report adheres to the requirements of that code: the background statement (part 1), overview of the remuneration policy (part 2 – detailing the current policy and future policy from 2019) and the implementation report (part 3).
Remuneration committee objectives for FY18
Despite the group's financial performance being severely impacted by challenging operating environment and the Listeria outbreak, in FY18, the remuneration committee sought to leverage the remuneration strategy to enable the attraction and retention of key skills to support delivery of the business strategy.
In a tough operating environment, the company succeeded in attracting key employees, further strengthening the Tiger Brands executive leadership team by recruiting new capabilities in certain business units: marketing, strategy and human resources.
Following the 2018 reorganisation of the group, the leadership team focused on embedding the new operating model, skilling employees to embrace new responsibilities in their roles and engaging teams to entrench new ways of working to execute the business strategy and deliver winning performance.
To ensure our remuneration policy remains competitive and fulfils the objective of attracting, motivating and retaining high-performing employees, we have reviewed our pay scales and other elements of the remuneration design after considering market benchmarks and capabilities required to deliver the business strategy.
The remuneration committee again engaged with shareholders on recent voting outcomes and analysed major points that affected their voting:
| Issue | Remuneration committee action/response | |
| Share appreciation rights (SARs) vesting scale does not include sufficient stretch | Revised scheme to be introduced from FY20 that will have more demanding targets. | |
| Lack of a return metric in short- and long-term incentive (STI and LTI) schemes | Return on net assets (RONA) included in key performance indicators for FY18, which influences the STI and the inclusion of return on invested capital (ROIC) as a performance metric in the LTI scheme for FY19 | |
| No clawback policy in place | A clawback and malus clause will be included in the remuneration policy from FY19 | |
| Limited disclosure on STI targets | Greater disclosure on STI scorecard in FY18 report | |
| Non-executive directors are paid hourly fees for extra work, which implies they could be paid for consultancy work. This may affect their ability to function independently | Effect payment of hourly fees in exceptional and extraordinary circumstances, subject to the approval by the Chief Executive Officer |
Shareholder input has been considered in our continued efforts to modernise and align our remuneration policy with business strategy execution and shareholder interests. Accordingly, we have:
- Refined our approach to linking our annual execution plans directly with business strategy by ensuring the appropriate focus of our STI metrics on growth, efficiencies, people and sustainability
- Revised our market anchor point for guaranteed pay from the 50th to 65th percentile of the national market and implemented a pay-progression model to ensure we are able to attract and motivate talent and core capabilities
- Increased focus to address any unjustifiable pay inequities
- Developed a clawback and malus policy to minimise risk
- Revised LTI performance metrics to align executive and shareholder interests.
Refer to the overview section of the report which discusses the remuneration elements and outlines key enhancements to our remuneration strategy from 2019.
Shareholder engagement
The remuneration committee is committed to shareholder engagement and will take the following steps if 25% or more of total votes exercised by shareholders at the upcoming annual general meeting (AGM) are against the remuneration policy or implementation report:
- Tiger Brands will issue a SENS announcement inviting dissenting shareholders to note their specific concerns andto engage with the company
- We will consider these concerns and report on the outcome of this engagement, and measures taken, in our next integrated report.
Focus areas for 2019
As we begin our new financial year, the remuneration committee is committed to staying abreast of remuneration market trends and best practice, business requirements, our responsibilities to our community as well as our shareholders to ensure our remuneration practices are aligned with our business strategy.
Key focus areas include aligning our people with business objectives through an integrated scorecard that has group/business and individual components to support strategy execution. We will also continue to actively monitor and address identified pay inequities to ensure we attract and retain key talent. Finally, we will review share instruments in the LTI scheme to further align executives' interests and commitment with shareholder value creation.
Voting at AGM
As required by King IV, the remuneration policy and implementation report detailed here will be tabled for separate non-binding advisory votes by shareholders at the upcoming AGM.
As required by the Companies Act, non-executive directors' fees for the coming year will be put to shareholders by way of a special resolution.
We encourage all shareholders to provide feedback on their position on the various voting requirements. We commit to engaging with shareholders as required to discuss issues of concern.
External advice to the committee in 2018
In reviewing our remuneration offering to ensure it is competitive, fair, ethical and transparent, we enlisted the services of PwC South Africa and Vasdex to assist us with design, market practice and survey data. The committee is satisfied that PwC and Vasdex are independent.
Mark Bowman
Chairman – Remuneration committee
21 November 2018
SECTION 2: OVERVIEW OF REMUNERATION POLICY
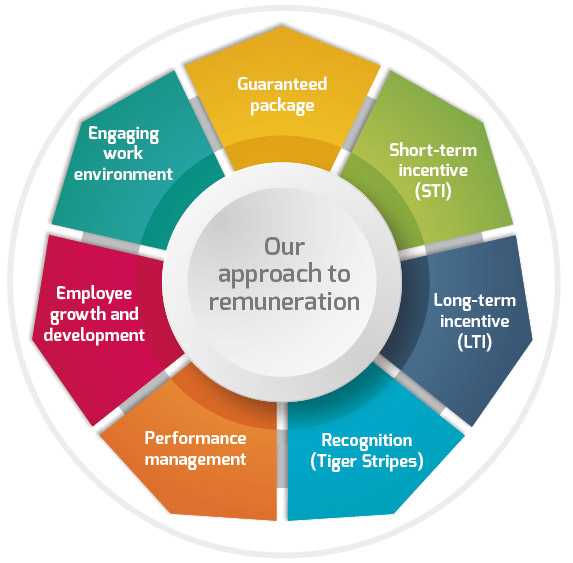
The Tiger Brands approach to remuneration is holistic, encompassing the monetary elements of reward as well as non-financial aspects such as growth, development and work environment.
Central tenets of our remuneration policy
To support our remuneration strategy, our remuneration policy is based on the following central tenets:
- Aligning strategic business performance with shareholder interests
- Providing a competitive reward offering to attract and retain talent that enables execution of our business strategy
- Rewarding and motivating winning performance across all levels in the organisation
- Build a strong foundation of fair and responsible pay.
Fair and responsible remuneration
The remuneration committee is committed to ensuring our remuneration policy and practices are fair, transparent and responsible. Key principles guiding this policy include:
- Motivating delivery of the company's strategic objectives while aligning strategy execution with internal and external stakeholder interests. As such, executive remuneration is determined by considering performance, complexity of the role, peer-group comparisons and market practice.
- Internal equity – we continually investigate and address any inequitable pay practices across the organisation. We have made a concerted effort to address income disparities, based on race, gender and performance. Any unjustifiable differences in pay and conditions of employment between employees at the same level are being addressed in line with the 'equal pay for work of equal value' philosophy.
- External equity – we conduct annual benchmarking exercises to understand economic trends and ensure all employees are paid a market-related salary, taking into consideration performance levels.
Guaranteed package (excluding bargaining unit employees)
Description |
Guaranteed package (GP) comprises base pay, allowances, retirement and medical benefits. It is reviewed annually based on personal performance (key performance indicators (KPIs) based on a balanced scorecard that includes financial and non-financial metrics), business performance (linked to budget), behaviours aligned with the values and market competitiveness (national and sector benchmarks) |
|||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Benchmarks |
Benchmarking for executive directors and prescribed officers is based on a peer group of companies. The peer group is determined using the closeness metric formula, based on:
Companies included in the peer group comprise:
|
|||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Anchor point |
Tiger Brands’ current pay position is at the 50th percentile (median) of the market, where a normal distribution around the median is to be expected based on individual employee performance, talent/potential, experience and, in certain instances, tenure |
|||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Benefits |
Benefits include retirement fund contributions, funeral cover, permanent health insurance, death-in-service cover, medical aid contributions and travel allowances (where applicable) |
|||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Changes for FY19 |
Market benchmarks indicate that our guaranteed package is not competitive in relation to our peers. In practice, we have had to pay significant premiums to source key talent externally. To address this challenge, we have taken a balanced approach and revised our anchor point for guaranteed package from the 50th percentile to the 65th percentile to attract and motivate talent to ensure we sustainably build core capability to execute our business strategy. We are implementing a pay-progression model to ensure we reward performance competitively and actively manage pay around our chosen anchor point. |
Short-term incentive
Description and link to strategy |
The primary intention of the STI is to improve business performance by focusing participants’ attention on key financial, strategic, functional and personal performance objectives (KPIs based on a balanced scorecard), which are aligned with the long-term business strategy for sustainable value creation.
|
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Calculation |
STI = Guaranteed Package (GP) x on-target % x business performance multiplier x personal performance multiplier |
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Target and maximum |
The following ranges of STI awards apply to the various categories of employees covered by this report:
Maximum STI amounts are based on the on-target % adjusted for the maximum potential ranges applicable to both the business performance multiplier (150%) and personal performance multiplier (175%). |
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Business performance multiplier |
The underlying values and weightings for each KPI are set and approved by the remuneration committee in advance of each year to determine parameters for the STI.
|
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Personal performance multiplier |
Personal performance measurement is based on a weighted combination of a balanced scorecard of metrics, typically comprising:
Taking into account the balanced scorecard and the individual KPIs, the personal performance multiplier is determined as follows:
|
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Changes for FY19 |
To incentivise execution of our strategic and tactical plans to deliver winning performance, the scheme has been revised from a multiplicative model to an additive model as follows: STI = GP x on-target % x {group performance factor (0 – 200%) + business unit performance factor (0 – 200%) + individual performance factor (0 – 200%)}. Predetermined weightings will be applied to each of the performance factors. The maximum STI that can be earned is 200% of the applicable on-target percentage. This drives high performance by explicitly creating line of sight in linking group, business unit and individual performance. An integrated STI scorecard for the group that includes financial and non-financial (sustainability) metrics is being implemented to align teams on a One Tiger bottom line. Payment of an STI is subject to the overriding condition that the group/business unit meets or exceeds its earnings before interest and tax (EBIT) entry threshold. Below is the group STI scorecard that will apply to the CEO, CFO, executive directors and prescribed officers:
The group, business unit and individual weightings applicable to the CEO, CFO, executive directors and prescribed officers are detailed below:
|
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Long-term incentive
Description |
Long-term incentive (management and above) There are three schemes operating for long-term incentives as part of the Tiger Brands 2013 Share Plan (LTIP):
Key elements of the LTIP include:
Vesting periods
Historical LTI informationPerformance shares The last awards of performance shares were made in February 2016 and in May 2016. The vesting of these awards would be determined by the company’s comparative total shareholder return (TSR) relative to the TSR of the constituent members of the FINDI 30 index. The vesting of the 2016 performance shares will thus be based on Tiger Brands’ relative TSR position over the three-year vesting period, as follows:
Any performance shares that do not vest at the end of the three-year period will be forfeited. SARs performance conditions for previous allocations For outstanding SARs allocated before December 2016, the performance vesting conditions are based on a targeted rate of 3% per annum real growth in HEPS over three-, four- and five-year periods. Percentage threshold levels for real HEPS growth and corresponding percentage of allocation to vest:
|
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Share appreciation rights |
The following ranges of SARs, based on the face value of awards, apply to the categories of staff covered by this report: |
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Value of awards |
|
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Calculation |
The number of SARs at award date is determined as follows: SARs = (GP x SARs multiple/share price) x PDT multiplier |
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Share price |
The share price is determined based on the volume-weighted average price (VWAP) for the 10 trading days before the issue date. |
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Vesting |
Vesting occurs according to the following pattern:
|
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Performance metrics |
Performance metrics that determine vesting (in addition to continued employment) are defined as:
Pro rata vesting on linear scale if HEPS growth > CPI but below CPI + GDP rate. Further vesting condition: Average annual return on capital over the relevant performance period must exceed the company’s weighted average cost of capital (WACC). |
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Fair value |
To illustrate the target and maximum outcomes of total remuneration as set out here , the face value of SARs was based on a defined % of GP (assuming ‘on-target’ and ‘maximum’ performance will be met), with the fair value of SARs calculated at 30% of this face value. |
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Bonus-matching shares |
The following multiples of bonus-matching shares, based on the face value of STI award, apply to the employee categories covered by this report: |
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Value of awards |
|
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Calculation |
The number of bonus-matching shares at award date is determined as follows: Bonus-matching shares = (actual STI x 50%/share price) x PDT multiplier |
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Share price |
The share price is determined based on the VWAP for the 10 trading days before the issue date. |
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Vesting |
Vesting occurs according to the following pattern:
|
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Performance metrics |
There are no further performance conditions to determine vesting, which is therefore time-based. The reason for no further vesting condition is that the quantum of bonus-matching shares is directly linked to the bonus. Performance is required ‘on the way in’ to earn the bonus. If STI targets are not met, no STI is earned, hence no bonus-matching shares will be allocated. |
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Fair value |
To illustrate the target and maximum outcomes of total remuneration set out here, the face value of bonus-matching shares was based on a defined % of STI earned. The fair value of the bonus-matching shares was calculated at 90% of this face value. |
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Deferred bonus shares and company-matching shares |
The CEO, CFO, executive directors, prescribed officers and members of the executive team may be granted deferred bonus shares and company matching shares on the following basis: Upon election by the individual, a percentage of the STI (25%, 33% or 50%) may be deferred and converted into deferred bonus shares, with additional company-matching shares being granted by the company. |
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Value of awards |
Deferred bonus shares and company-matching shares are only awarded if a bonus/STI was earned. Hence performance is ‘on the way in’. |
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Calculation |
The number of deferred bonus shares and company-matching shares, at award date, is determined as: Deferred bonus shares and company-matching shares = (actual STI deferred x 2/share price |
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Share price |
The share price is determined based on the VWAP for the 10 trading days before the issue date. |
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Vesting |
Vesting for deferred and company-matching shares occurs according to the following pattern:
|
|||||||||||||||||||||||||||||||||||||||||||||||||||||
| Performance metric | There are no further performance conditions to determine vesting. |
|||||||||||||||||||||||||||||||||||||||||||||||||||||
| Fair value | To illustrate the target and maximum outcomes of total remuneration set out here, the face value of deferred bonus shares and company-matching shares was calculated on the assumption that the maximum of 50% of the STI will be deferred. The fair value was calculated at 90% of this face value. |
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Dilution |
Under the rules of the Tiger Brands Phantom Cash Option Scheme (replaced by the LTIP), at any point the aggregate number of unexercised phantom options is limited to 10% of the total issued share capital of the company. At 30 September 2018, aggregate outstanding options under the scheme represented 0,02% (2017: 0,06%) of the company’s issued share capital. The maximum aggregate number of shares that may be acquired by participants under the LTIP and any other share plan may not exceed 5,5 million shares; and for any one participant 550 000 shares. In determining these limits, shares acquired through the JSE and transferred to participants are not considered. At 30 September 2018, the aggregate number of shares that may be acquired by participants under the various schemes was 1 898 112 (2017: 1 742 012), which represents approximately 1% of the number of issued ordinary shares. This is in line with market practice. |
|||||||||||||||||||||||||||||||||||||||||||||||||||||
BEE schemes |
Two schemes were previously established as part of the company’s black empowerment strategy:
|
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Changes for FY19 |
To focus on our long-term strategy execution, we have revised LTI performance conditions for share appreciation rights by including ROIC. As such, we have implicitly aligned the interests of our shareholders and employees. Vesting conditions are summarised below:
|
|||||||||||||||||||||||||||||||||||||||||||||||||||||
Minimum shareholding policy
Description |
We have a minimum shareholding policy, where executives are expected to build up their personal shareholding in the company to at least 150% of GP (for CEO) and 100% of GP for other exco members. Executives have six years to build up these holdings. Executives who were in service when the policy was adopted have six years to build up their shareholding from date of adoption. Executives appointed after adoption have six years to build their shareholding from date of appointment. They may use a portion of their STI, any vesting LTIs or their own resources to acquire these shares.
For FY19, we have increased the minimum shareholding for the CEO from 150% to 200% to align with market practice. |
Clawback and malus
Description |
From FY19, we have implemented a clawback and malus policy to minimise risk. The central tenets of the policy include: In the event that the remuneration committee, in consultation with the board and/or any committee of the board, believes that a trigger event has occurred, it has full discretion to reduce, in part or whole, unvested variable remuneration before the end of the vesting or payment period – malus. It is the responsibility of the remuneration committee, in consultation with the board and/or any committee of the board, to implement clawback for the whole or portion of vested variable remuneration in the event of a trigger event over a period of three years from the date on which payment was made of such vested variable remuneration. Trigger events include, but are not limited to:
|
Illustrating potential remuneration outcomes
The variable pay arrangements described on the previous pages have various potential outcomes. These outcomes could be from zero (minimum) to the expected level of performance outcomes (target) to the maximum potential variable pay outcomes (maximum).
In the illustrations presented below, it should be noted that:
- STI represents the cash component of short-term performance
- LTI represents the total of share appreciation rights awards, bonus-matching awards, deferred bonus shares and company-matching shares.
CEO
The potential total remuneration outcomes for the CEO are as follows:
| R’000 | GP | STI | LTI | Total | ||||||
| Minimum | 9 084 | 0 | 0 | 9 084 | ||||||
| On-target | 9 084 | 5 450 | 5 723 | 20 256 | ||||||
| Maximum | 9 084 | 14 307 | 16 146 | 39 536 |
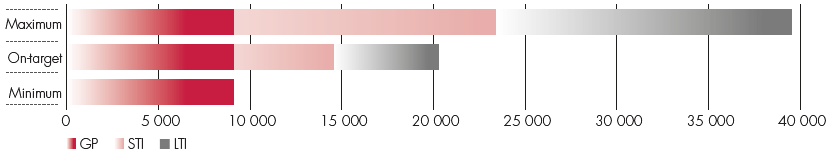
CFO
The potential total remuneration outcomes for the CFO are as follows:
| R’000 | GP | STI | LTI | Total | ||||||
| Minimum | 6 550 | 0 | 0 | 6 550 | ||||||
| On-target | 6 550 | 3 930 | 4 126 | 14 606 | ||||||
| Maximum | 6 550 | 10 316 | 11 642 | 28 508 |
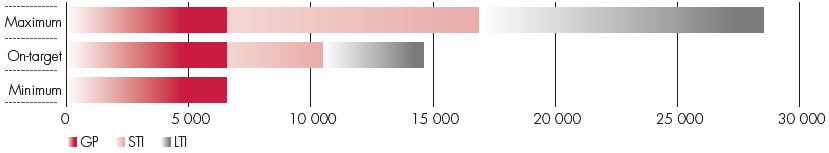
Prescribed officers (on average)
The potential total remuneration outcomes for prescribed officers are as follows:
| R’000 | GP | STI | LTI | Total | ||||||
| Minimum | 4 751 | 0 | 0 | 4 751 | ||||||
| On-target | 4 751 | 2 375 | 2 637 | 9 763 | ||||||
| Maximum | 4 751 | 6 235 | 7 180 | 18 166 |
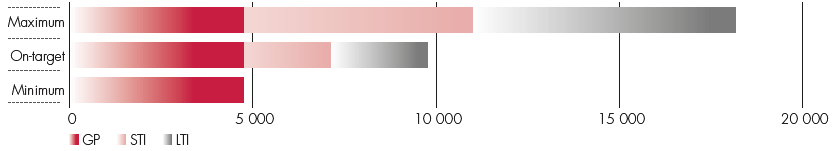
Group executive committee (on average)
The potential total remuneration outcomes for other members of the group executive committee are as follows:
| R’000 | GP | STI | LTI | Total | ||||||
| Minimum | 3 790 | 0 | 0 | 3 790 | ||||||
| On-target | 3 790 | 1 807 | 2 044 | 7 641 | ||||||
| Maximum | 3 790 | 9 138 | 9 455 | 22 384 |

Executive service contracts
Senior executives are employed full-time under standard agreements, with a notice period of three months. We strive to bind all senior executives by a restraint-of-trade agreement. To the extent that executives have access to proprietary business insights and intellectual property, Tiger Brands will enforce the agreement should they join a competitor. The restraint comprises a three-month notice period or three months’ special leave (paid as a three-month lump sum (based on guaranteed package) on termination).
Payments on termination of employment
| Remuneration policy component | Voluntary termination (ie resignation) |
Involuntary termination (retrenchment, retirement, death) |
||
| Guaranteed package | Paid up to last date of service | Paid up to last date of service including notice period, where applicable | ||
| Medical aid | Benefit continues to last date of service | Benefit continues up to last date of service. Employees who qualify for post-retirement medical aid funding will continue to receive the employer contribution with effect from their normal retirement date. | ||
| Retirement and risk plans | Employer contributions paid until last date of service. Employee is entitled to the value of the investment | |||
| Other benefits | Not applicable | Severance package – 1 or 2 weeks for every completed year of service in terms of the relevant rules | ||
| Short-term incentive | No pro rata bonus paid | Pro rata STI payment (based on extent of achieving specified financial and strategic targets for the period and a personal performance agreement being in place at the date of exit) | ||
| Long-term incentives | All unvested awards (other than certain deferred bonus shares) will be forfeited | Depending on the nature of the unit (ie SARs, bonus-matching shares, deferred bonus shares or company-matching shares) and reasons for termination, a participant may retain all units or a pro rata portion. Accelerated vesting and settlement of retained units may apply in certain circumstances. |
External board appointments
Tiger Brands encourages members of the executive committee to consider accepting appropriate opportunities to serve as non-executive directors on the main board or committees of external companies. We believe this encourages our executives to broaden their skills base and experience.
Under a formal policy, an executive is limited to one substantive outside directorship. The chairman of the Tiger Brands board, chairman of the nominations committee, and chairman of the remuneration committee are required to authorise these appointments based on a recommendation from the CEO. Other than in respect of their appointment to the boards of associate companies, directors’ fees under this policy may be retained by the individual. Other than associate companies, Tiger Brands currently has no executive members serving as non-executive directors on the main boards or committees of external companies.
Details of exco members serving on the boards of associate companies appear here.
Non-executive directors
Fees and approval process
Non-executive directors are paid an annual retainer that reflects their overall contribution and input to the company, and not just for attendance at board and committee meetings.
Fees are reviewed annually and increases are implemented in March after approval at the AGM. A bespoke survey is conducted every two years to benchmark these fees against South African companies listed on the JSE, based on market capitalisation, revenue, total assets and number of employees. These are similar metrics to that of the benchmark group for executive directors and prescribed officers but further expanded to include the diversity of skill and calibre required on the board or relevant committee.
Companies included in the peer group are detailed below:
| RCL Foods Limited | The Spar Group Ltd | MTN Group Ltd | ||
| Blue Label Telecoms Ltd | Clicks Group Ltd | Vodacom Group Ltd | ||
| Pioneer Food Group Ltd | Sappi Group | Standard Bank Group Ltd | ||
| Telkom SA SOC Ltd | Woolworths Holding Ltd | Datatec Ltd | ||
| Distell Group Ltd | Aspen Pharmacare Holdings Ltd | JD Group Ltd |
Targeted remuneration for FY18 is the 50th percentile of the peer group. In line with the revision of our internal anchor point, from FY19 the targeted remuneration will be moved to the 65th percentile of the peer group.
Non-resident non-executive directors are paid a premium in comparison to resident directors. The table below shows the range of the premium paid to non-resident non-executive directors across large JSE-listed organisations in various industries:
| Target position | Premium for non-resident non-executive directors | |
| Minimum | 85% | |
| Maximum | 307% | |
| Average | 185% | |
| Median | 174% |
The median for non-resident non-executive directors’ fees is at a premium of 174% above resident fees. Tiger Brands currently pays a premium of 130% for non-resident non-executive directors, which is below the market median.
The chairman does not receive any additional remuneration for participating in committees of the board. Non-executive directors who perform services outside the scope of their ordinary duties will not receive additional remuneration. Shareholder approval will be sought for increasing non-executive directors’ fees, including fees paid for attending special board meetings. Details of proposed increases for 2019 appear in the notice of AGM of shareholders to be held on 19 February 2019.
Details of non-executive directors’ fees paid in the review period appear here.
SECTION 3: IMPLEMENTATION REPORT
Voting outcomes
Results of voting at the 2018 and 2017 AGM are indicated below:
| % vote in favour | February 2018 | February 2017 | |
| Remuneration policy | 73,41% | 53,80% | |
| Remuneration implementation | 82,59% | n/a | |
| Non-executive directors’ fees | 99,80% | 99,95% |
Summary of shareholder feedback and responses
The following common themes were noted by shareholders:
| Shareholder feedback | Tiger Brands response and actions | |
| A sign-on bonus was paid; however, reasons for the payment were not sufficiently explained. There is a preference for sign-on bonuses to include restricted shares. | Should any sign-on bonuses be awarded in future, greater detail on reasons for the award will be provided to improve disclosure. In addition, for executive appointments in FY18, all sign-on LTI awards were made in the form of SARs, which have vesting conditions attached. Y Maharaj was paid a sign-on bonus of R1 000 000. In addition, he will receive a share allocation of 20 000 Tiger Brands shares and 17 000 Adcock Ingram shares in terms of the Tiger Brands Black Managers Trust Scheme. The sign-on bonus and share award are in lieu of STI and LTI forfeited at his former employer. Other strategic appointments to the executive committee and sign-on payments were made, as disclosed in the annual financial statements here. | |
| Matching plans are not believed to be best practice, as these provide a mechanism for additional shares to be awarded without any performance conditions attached. | The quantum of company matching shares (ie 100% matching) is directly linked to the STI. Performance is required ‘on the way in’ to earn the STI. Furthermore, company matching shares are only awarded on deferred bonus shares (which requires a voluntary deferral of the STI). Company matching shares are considered best practice on voluntary deferrals, and promote good behaviour (by encouraging the deferral of a portion of the STI, which supports a long-term view of performance and demonstrates commitment to the company). | |
| The SARs vesting scale does not build in sufficient stretch. At entry level, HEPS growth should be in line with CPI+GDP, with pro rata vesting on a linear scale above this level. HEPS growth above CPI but below CPI+GDP should result in no payment. | Performance conditions for SARs are usually viewed as an underpin, with the embedded condition of share price growth being the primary objective. Market benchmarks for SARs targets are usually more moderate than those for full-value share awards. | |
| Restricted share awards in the form of bonus matching shares, bonus deferral shares and company-matching shares are not subject to performance conditions. | The performance criteria are determined ‘on the way in’, through individual performance ratings and STI financial targets. If no STI is earned, no restricted shares are awarded. | |
| Performance measures should include both financial and non-financial (sustainability) KPIs. | The STI is a multiplier scheme, aligned with global best practice, using a business modifier that primarily focuses on financial metrics to ensure alignment with shareholder outcomes, as well as a personal performance modifier, which differentiates based on achieving agreed strategic initiatives (including sustainability targets), as well as an individual’s KPIs. This ensures personal accountability for the financial and strategic aspects of the business. From FY19, a group-wide STI scorecard, which includes financial and non-financial metrics (sustainability), has been introduced. The LTI scheme also has a performance differentiator (PDT tool) which ensures personal accountability for non-financial KPIs. |
|
| The LTI scheme has a minimum hurdle rate which equates to the company’s cost of capital. Hurdles to measure operational returns in excess of cost of capital plus an appropriate margin are recommended. | Introducing an additional performance metric into the SARs element of the LTI scheme for FY19. There will be two metrics, each with an equal weighting: 50% HEPS growth (as per the current scheme) and 50% ROIC (new metric). | |
| Individual maximum limits for STI and LTI schemes are not explicit. | Individual maximum limits are set in terms of the STI and LTI schemes. This has been clarified in the FY18 remuneration report. | |
| No clawback policy in place. | A clawback and malus clause has been included in the remuneration policy from FY19. | |
| Limited disclosure on STI targets. | STI target disclosure has been enhanced in the FY18 remuneration report. | |
| The personal performance multiplier in the STI is an output of an individual’s KPIs, which focus on long-term business goals. It is recommended that these KPIs be disclosed. | STI scorecards for the group and operational/functional units to be introduced for FY19. The scorecards contain both financial and strategic objectives. | |
| Lack of a return on capital metric in the STI scheme. | RONA has been included in KPIs for FY18. | |
| An EBIT weighting of 35% is excessive. It may provide sufficient incentive to leadership to pursue mergers and acquisitions which come at the expense of HEPS and DPS. To align better with shareholder interests, a per-share metric is recommended. | This concern is already fully addressed in the rules of the STI scheme. In the event of an unbudgeted acquisition or disposal, the remuneration committee will adjust reported results for the impact of such acquisition or disposal to ensure actual business performance is directly comparable with agreed financial targets. | |
| There is no distinction in non-executive director fees between a base fee and an attendance fee per meeting as per King III. | As part of the non-executive director survey, benchmarking is conducted on a holistic fee per committee, which includes a base fee, preparation and attendance fee. It is most common to just pay a retainer. King IV has replaced King III and no longer requires this separation. In addition, most companies pay a retainer rather than a per-meeting fee, and there is some sentiment in the market that a retainer is more appropriate as it reflects the director’s inputs throughout the year, not just in meetings. | |
| Non-executive directors are paid hourly fees for extra work, which implies they could be paid for consultancy work. This may negatively impact their ability to function independently. | Payment of hourly fees will be discontinued from FY19. Under exceptional circumstances, if it is deemed appropriate to pay hourly fees, the specific resolution to approve remuneration to non-executive directors for attending unscheduled meetings and performing extraordinary additional work will be split to allow shareholders to exercise their right in voting against the payment of hourly fees. | |
| Non-resident non-executive directors are paid a premium of 130% relative to resident directors. The rationale for the high premium should be disclosed. | Considering the need to have a team of non-executive directors who are both commercially and technically strong, as well as to ensure that there is diversity and independence in strategic decision making, we have appointed non-resident non-executive directors. Market benchmarking indicates that the 130% premium is on the lower side for non-resident directors. Non-resident non-executive director fees are usually between two and three times fees paid to SA non-executive directors. This has been contextualised in the FY18 remuneration report in the outcome of the market survey. |
For the review period, in addition to financial targets, the following KPIs as per the balanced scorecard applied to the CEO, CFO and Prescribed officers. The level of achievement is reflected alongside each KPI:
| KPIs scorecard | ||||||||||||||||||||||||||||||||||||||||||||
|
|
|
|
|||||||||||||||||||||||||||||||||||||||||
 |
Met |  |
Partially met |  |
Not met |
The implementation report details the outcomes of implementing the approved policy in the current financial year.
2018 guaranteed package
The following increases to guaranteed packages were implemented in the reporting period for executive directors and prescribed officers. New amounts were effective from 1 December 2017:
| 1 Dec 2017 to 30 Nov 2018 R |
1 Dec 2016 to 30 Nov 2017 R |
% increase | ||||
| Executive directors | ||||||
| LC Mac Dougall | 9 083 550 | 8 610 000 | 6 | |||
| NP Doyle | 6 549 750 | 6 150 000 | 7 | |||
| CFH Vaux* | 5 236 335 | 4 963 351 | 5 | |||
| Prescribed officers | ||||||
| AG Kirk** | 4 842 563 | 4 590 107 | 6 | |||
| PW Spies | 4 853 000 | 4 600 000 | 6 | |||
| Y Maharaj*** | 4 850 000 | n/a | ||||
| PD Sithole**** | 4 549 157 | 3 973 063 | 14,5 |
| * | Stepped down from the board on 20 February 2018. | |
| ** | Resigned on 31 August 2018. | |
| *** | Joined on 1 July 2018. | |
| **** | Categorised as prescribed officer 1 October 2017 in line with the new operating model. |
The average increase of 6% (2017: 4,1%) for executive directors and prescribed officers compares to an average of 6% (2017: 4%) for the rest of the company.
2018 short-term incentive
As indicated in the policy section, the STI for executive directors and prescribed officers is based on the combination of a business multiplier and personal performance multiplier.
Executive directors
The business multiplier for executive directors is weighted according to the table below. Results for FY18 were as follows:
| Target | Achievement | |||||||
| Threshold | On-target | Stretch | ||||||
| KPI | Weighting | Business multiplier = 50% |
Business multiplier = 100% |
Business multiplier = 150% |
Actual result |
Weighted result |
||
| HEPS | 35% | 94% | 100% | 104% | <94% | 0% | ||
|---|---|---|---|---|---|---|---|---|
| EBIT | 35% | 91,80% | 100% | 104% | <91,80% | 0% | ||
| Volume growth | 15% | 75% | 100% | 140% | <75% | 0% | ||
| Net working capital | 15% | 101% | 100% | 97% | >101% | 0% | ||
| Total | 100% | 0% | ||||||
| Notes: | |
| 1. | The targeted percentages for “threshold”, “on-target” and “stretch” as set out above per KPI represent the targeted percentage achievement of the underlying budgeted amounts. |
| 2. | Linear vesting will apply if the actual result falls between “threshold” and “on-target” or between “target” and “stretch”. |
Targets for the STI for 2017 and 2018 were not met, hence no STI was paid.
The FY18 personal performance multiplier is the aggregated result of assessing the KPIs for the relevant executive, as follows:
| LC Mac Dougall | NP Doyle | CFH Vaux* | ||||||||||||||
| Executive directors KPIs | Weighting | Not met |
Partially met |
Met | Exceeded | Not met |
Partially met |
Met | Exceeded | Not met |
Partially met |
Met | Exceeded | |||
| Top-tier financial results | ||||||||||||||||
| Revenue | |
|
|
|||||||||||||
| Gross margin | |
|
|
|||||||||||||
| Productivity/cost savings | |
|
|
|||||||||||||
| Return on net assets | |
|
|
|||||||||||||
| Market performance | ||||||||||||||||
| Market share | |
|
|
|||||||||||||
| On-shelf availability | |
|
|
|||||||||||||
| Innovation rate | |
|
|
|||||||||||||
| Power in mind (brand health) | |
|
|
|||||||||||||
| Compliance | ||||||||||||||||
| Zero level 1 audit findings | |
|
|
|||||||||||||
| Reduction in consumer complaints | |
|
|
|||||||||||||
| Safety (LTIFR) | |
|
|
|||||||||||||
| BBBEE implementation | |
|
|
|||||||||||||
| People | ||||||||||||||||
| Improved employee engagement | |
|
|
|||||||||||||
| Employee development plans in place | |
|
|
|||||||||||||
| Diversity and inclusion | |
|
|
|||||||||||||
| Individual KPIs | |
|
|
|||||||||||||
No STI was awarded to executive directors as illustrated below:
| GP* R |
On-target % |
Business multiplier % |
Personal performance multiplier % |
STI award 2018** R |
STI award 2017** R |
||||||
| LC Mac Dougall | 9 083 550 | x | 60 | x | 0 | x | 100 | = | 0 | 0 | |
|---|---|---|---|---|---|---|---|---|---|---|---|
| NP Doyle | 6 549 750 | x | 60 | x | 0 | x | 100 | = | 0 | 0 | |
| CFH Vaux*** | 5 236 335 | x | 60 | x | 0 | x | 110 | = | 0 | 0 |
| * | GP at 30 September 2018. |
| ** | Includes value of bonus deferral. |
| *** | Stepped down as an executive director in February 2018. |
Prescribed officers
The business multiplier for prescribed officers is weighted according to the table below. The results for FY18 were as follows:
| Target | Achievement | ||||||||
| Threshold | Target | Stretch | |||||||
| KPI | Weighting | Business multiplier = 50% |
Business multiplier = 100% |
Business multiplier = 150% |
Actual result |
Weighted result |
|||
| EBIT | 70% | 91,80% | 100% | 104% | <91,80% | 0% | |||
|---|---|---|---|---|---|---|---|---|---|
| Volume growth | 15% | 75% | 100% | 140% | <75% | 0% | |||
| Net working capital | 15% | 101% | 100% | 97% | >101% | 0% | |||
| Total | 100% | 0% | |||||||
| Notes: | |
| 1. | The targeted percentages for “threshold”, “on-target” and “stretch” as set out above per KPI represent the targeted percentage achievement of the underlying budgeted amounts. |
| 2. | Linear vesting will apply if the actual result falls between “threshold” and “on-target” or between “target” and “stretch”. |
The overall business multiplier result for prescribed officers is 0% in comparison to 101,1% in 2017.
The FY18 personal performance multiplier is the aggregated result of assessing the KPIs for the relevant executive, as follows:
| PW Spies | PD Sithole | |||||||||
| Prescribed officers KP | Not met |
Partially met |
Met | Exceeded | Not met |
Partially met |
Met | Exceeded | ||
| Top-tier financial results | ||||||||||
| Revenue | |
|
||||||||
| Gross margin | |
|
||||||||
| Productivity/cost savings | |
|
||||||||
| Return on net assets | |
|
||||||||
| Market performance | ||||||||||
| Market share | |
|
||||||||
| On-shelf availability | |
|
||||||||
| Innovation rate | |
|
||||||||
| Power in mind (brand health) | |
|
||||||||
| Compliance | ||||||||||
| Zero level 1 audit findings | |
|
||||||||
| Reduction in consumer complaints | |
|
||||||||
| Safety (LTIFR) | |
|
||||||||
| BBBEE implementation | |
|
||||||||
| People | ||||||||||
| Improved employee engagement | |
|
||||||||
| Employee development plans in place | |
|
||||||||
| Diversity and inclusion | |
|
||||||||
| Individual KPIs | |
 |
||||||||
No STI was awarded to prescribed officers as illustrated below:
| GP* R |
On-target % |
Business multiplier % |
Personal performance multiplier % |
STI award 2018** R |
STI award 2017** R |
||||||
| AG Kirk*** | – | x | 50 | x | 0 | x | 0 | = | – | 2 320 310 | |
|---|---|---|---|---|---|---|---|---|---|---|---|
| PW Spies | 4 853 000 | x | 50 | x | 0 | x | 110 | = | – | 1 782 738 | |
| Y Maharaj**** | 4 850 000 | x | 50 | x | 0 | x | 0 | = | – | – | |
| PD Sithole***** | 4 549 157 | x | 50 | x | 0 | x | 120 | = | – | 2 610 911 |
| * | GP as at 30 September 2018. | |
| ** | Includes value of bonus deferral. | |
| *** | Resigned on 31 August 2018. | |
| **** | Appointed 1 July 2018. | |
| ***** | Categorised as prescribed officer 1 October 2017 in line with the new operating model. |
2018 long-term incentive
Long-term incentive awards made during the year to executive directors and prescribed officers are set out below:
| SARs | Bonus-matching shares | Deferred bonus shares and company-matching shares |
||||||||||||||
| Name | PDT multiplier*** |
GP | Award % |
Face value |
Number | STI** | Award % |
Face value |
Number | Match % |
Face value |
Number | ||||
| LC Mac Dougall* | 100% | 9 083 550 | 41 | 3 725 906 | 8 990 | – | 50 | – | – | 100 | – | – | ||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| NP Doyle* | 200% | 6 549 750 | 145 | 18 994 244 | 45 830 | – | 50 | – | – | 100 | – | – | ||||
| CFH Vaux* | 0% | 5 236 335 | – | – | – | – | – | – | – | 100 | – | – | ||||
| Expected value (based on fair value) | |||||
| Name | SARS | Bonus- matching shares |
Deferred bonus shares and company-matching share |
||
| LC Mac Dougall* | 1 117 772 | – | – | ||
|---|---|---|---|---|---|
| NP Doyle* | 5 698 273 | – | – | ||
| CFH Vaux* | – | – | – | ||
| * | Allocated on 11 December 2017 at a VWAP of R414,45. | |
| ** | STI in respect of the year ended 30 September 2017. | |
| *** | A performance differentiation tool (PDT) is used to modify the standard quantum of SARs and bonus-matching shares, based on an individual’s personal performance, leadership and ability. This is a discretionary percentage ranging from 0% to 200%. |
Due to the executive directors STI targets not being met in FY17 performance, no bonus-matching and subsequently deferred bonus shares and company-matching shares were awarded to executive directors. Only share appreciation rights were awarded. Bonus matching shares, deferred bonus shares and company matching shares were awarded to Prescribed officers in addition to Share Appreciation Rights as the Prescribed officers STI targets were met.
| SARs | Bonus-matching shares | Deferred bonus shares and company-matching shares |
||||||||||||||
| Name | PDT multiplier*** |
GP | Award % |
Face value |
Number | STI** | Award % |
Face value |
Number | Match % |
Face value |
Number | ||||
| P Spies* | 137,5% | 4 853 000 | 110 | 7 339 910 | 17 710 | 1 782 738 | 50 | 1 226 772 | 2 960 | 100 | 1 786 280 | 4 310 | ||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| AG Kirk* | 137,5% | 4 842 563 | 110 | 7 327 476 | 17 680 | 2 320 310 | 50 | 1 595 633 | 3 850 | 100 | 2 320 920 | 5 600 | ||||
| PD Sithole* | 200,0% | 4 549 157 | 110 | 10 008 968 | 24 150 | 2 610 911 | 50 | 2 611 035 | 6 300 | – | – | – | ||||
| Expected value (based on fair value) | |||||
| Name | SARS | Bonus- matching shares |
Deferred bonus shares and company-matching share |
||
| P Spies* | 2 201 973 | 1 104 095 | 1 607 652 | ||
|---|---|---|---|---|---|
| AG Kirk* | 2 198 243 | 1 436 069 | 2 088 828 | ||
| PD Sithole* | 3 002 690 | 2 349 932 | – | ||
| * | Allocated on 11 December 2017 at a VWAP of R414,45. | |
| ** | STI in respect of the year ended 30 September 2017. | |
| *** | A performance differentiation tool (PDT) is used to modify the standard quantum of SARs and bonus-matching shares, based on an individual’s personal performance, leadership and ability. This is a discretionary percentage ranging from 0% to 200%. |
LTI awards vesting or with a performance period ending in 2018
The outcome for awards due to vest in FY18, and whose performance conditions ended by 30 September 2018, are shown below. This applies to all eligible participants.
| LTI measures | ||||||
| LTI allocation | Total shareholder return |
Real HEPS growth |
Performance condition result (% vesting) |
|||
| Company-matching shares granted in 2015** | n/a | n/a | 100% (time-based vesting) | |||
| Deferred bonus shares granted in 2015** | n/a | n/a | 100% (time-based vesting) | |||
| Bonus-matching shares granted in 2015** | n/a | n/a | 100% (time-based vesting) | |||
| Performance shares granted in 2015**# | |
n/a | 175% | |||
| Phantom cash share options granted in 2013 – third tranche**@ | n/a | |
0%* | |||
| Share appreciation rights granted in 2013 – third tranche** | n/a | |
0% | |||
| Share appreciation rights granted in 2014 – second tranche** | n/a | |
100% | |||
| Share appreciation rights granted in 2015 – first tranche** | n/a | |
27% | |||
| * | Only 50% of allocation subject to performance conditions. | |
| ** | In general, LTI allocations vested in 2018. However, the vesting date is extended for certain employees as a result of them being included in an employer-enforced voluntary closed period. | |
| # | Performance shares are no longer awarded. The last allocation was in May 2016. | |
| @ | Phantom cash share options are no longer awarded. The last allocation was in February 2013. |
|
Met | |
Partially met | |
Not met |
Payments for termination of office
No additional payments were made for executives terminating office.
Compliance with remuneration policy
There were no deviations from the remuneration policy in the financial year.
Single total figure of remuneration
The following tables disclose total remuneration received and receivable by executive directors and prescribed officers for the period 1 October 2017 to 30 September 2018:
Executive directors
| LC Mac Dougall | NP Doyle | CFH Vaux* | |||||||||||||||||
| Remuneration element | FY18 R |
FY17 R |
% | FY18 R |
FY17 R |
% | FY18 R |
FY17 R |
% | ||||||||||
| Basic salary | 8 511 653 | 8 058 719 | 5 497 977 | 5 211 772 | 1 967 786 | 4 531 406 | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Retirement funding | 339 880 | 429 695 | 913 148 | 923 969 | 145 875 | 406 707 | |||||||||||||
| Other benefits | 153 092 | 149 432 | 72 000 | 72 000 | 22 648 | 51 504 | |||||||||||||
| Guaranteed package | 9 004 625 | 8 637 846 | 6 483 125 | 6 207 742 | 2 136 309 | 4 989 618 | |||||||||||||
| Short-term incentive | – | – | – | – | – | – | |||||||||||||
| Cash remuneration | 9 004 625 | 8 637 846 | 6 483 125 | 6 207 742 | 2 136 309 | 4 989 618 | |||||||||||||
| SARs | – | – | – | – | 725 158 | – | |||||||||||||
| Bonus-matching shares | – | – | – | – | – | – | |||||||||||||
| Deferred bonus shares and company-matching shares | – | – | – | – | – | – | |||||||||||||
| Total remuneration | 9 004 625 | 8 637 846 | 4,2 | 6 483 125 | 6 207 742 | 4,4 | 2 861 467 | 4 989 618 | |||||||||||
Prescribed officers
| AG Kirk** | PW Spies | ||||||||||||
| Remuneration element | FY18 R |
FY17 R |
% | FY18 R |
FY17 R |
% | |||||||
| Basic salary | 3 860 556 | 3 955 010 | 4 029 942 | 2 343 743 | |||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Retirement funding | 316 384 | 390 999 | 344 639 | 250 723 | |||||||||
| Other benefits | 220 000 | 240 000 | 408 446 | 2 002 282 | |||||||||
| Guaranteed package | 4 396 940 | 4 586 009 | 4 783 027 | 4 596 748 | |||||||||
| Short-term incentive | – | 2 320 310 | – | 1 782 738 | |||||||||
| Cash remuneration | 4 396 940 | 6 906 319 | 4 783 027 | 6 379 486 | |||||||||
| SARs | – | – | – | – | |||||||||
| Bonus-matching shares | – | – | – | – | |||||||||
| Deferred bonus shares and company-matching shares | – | – | – | – | |||||||||
| Total remuneration | 4 396 940 | 6 906 319 | (36,3) | 4 783 027 | 6 379 486 | (25,0) | |||||||
** Resigned on 31 August 2018.
| Y Maharaj *** | PD Sithole | ||||||||||||
| Remuneration element | FY18 R |
FY17 R |
% | FY18 R |
FY17 R |
% | |||||||
| Basic salary | 1 021 587 | 3 988 160 | 3 435 295 | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Retirement funding | 84 797 | 344 981 | 363 047 | ||||||||||
| Other benefits | 1 106 116 | 141 624 | 120 000 | ||||||||||
| Guaranteed package | 2 212 500 | 4 474 765 | 3 918 342 | ||||||||||
| Short-term incentive | – | – | 2 610 911 | ||||||||||
| Cash remuneration | 2 212 500 | 4 474 765 | 6 529 253 | ||||||||||
| SARs | – | – | – | ||||||||||
| Bonus-matching shares | – | – | – | ||||||||||
| Deferred bonus shares and company-matching shares | – | – | – | ||||||||||
| Total remuneration | 2 212 500 | 4 474 765 | 6 529 253 | (31,5) | |||||||||
| *** | Paid a combination of a sign on bonus (R1 000 000) and share allocation (20 000 Tiger Brands shares and 17 000 Adcock Ingram shares in respect of the Tiger Brands Black Managers Trust), still to be allocated, in lieu of STI and LTI forfeited at his former employer. |
Number and value of LTI share awards
Disclosure of the quantum and value of awards for the CEO and CFO outstanding at the beginning of the reporting period, as well as new awards made in the period, are provided in the tables here , with the cash value of awards settled during the reporting period indicated in the value-based tables.
Schedule of LTI awards
Unvested awards and cash flow from settling LTI awards for the CEO and CFO are tabulated below:
| Name and awards | Award date | Vesting date |
Grant share price at award ZAR |
Opening number |
Granted during the year |
Forfeited during year |
Performance condition achieved |
Settled during the year |
|
| LC Mac Dougall | |||||||||
| 2016 deferred bonus shares | 07/12/2016 | 07/12/2019 | – | 650 | – | – | – | – | |
| 2016 company-matching shares | 07/12/2016 | 07/12/2019 | – | 650 | – | – | – | – | |
| 2016 bonus-matching shares | 07/12/2016 | 07/12/2019 | – | 650 | – | – | – | – | |
| 2016 performance shares | 24/05/2016 | 24/05/2019 | – | 8 160 | – | – | – | – | |
| 2016 SARs | 24/05/2016 | 24/05/2019 | 341,68 | 12 000 | – | – | – | – | |
| 24/05/2020 | 341,68 | 12 000 | – | – | – | – | |||
| 24/05/2021 | 341,68 | 12 000 | – | – | – | – | |||
| 2016 SARs | 07/12/2016 | 07/12/2019 | 395,97 | 10 946 | – | – | – | – | |
| 07/12/2020 | 395,97 | 10 947 | – | – | – | – | |||
| 07/12/2021 | 395,97 | 10 947 | – | – | – | – | |||
| 2017 SARs | 11/12/2017 | 11/12/2020 | 414,45 | – | 2 996 | – | – | – | |
| 11/12/2021 | 414,45 | – | 2 997 | – | – | – | |||
| 11/12/2022 | 414,45 | – | 2 997 | – | – | – | |||
| Total | 78 950 | 8 990 | – | – | – | ||||
| NP Doyle | |||||||||
| 2015 company-matching shares | 03/12/2015 | 03/12/2018 | – | 2 688 | – | – | – | – | |
| 2015 deferred bonus shares | 03/12/2015 | 03/12/2018 | – | 2 688 | – | – | – | – | |
| 2016 company-matching shares | 07/12/2016 | 07/12/2019 | – | 1 060 | – | – | – | – | |
| 2016 deferred bonus shares | 07/12/2016 | 07/12/2019 | – | 1 060 | – | – | – | – | |
| 2015 bonus-matching shares | 04/02/2015 | 04/02/2018* | – | 2 320 | – | – | – | – | |
| 2016 bonus-matching shares | 09/02/2016 | 09/02/2019 | – | 1 330 | – | – | – | – | |
| 2016 bonus-matching shares | 07/12/2016 | 07/12/2019 | – | 1 590 | – | – | – | – | |
| 2015 performance shares | 04/02/2015 | 04/02/2018* | – | 2 490 | – | – | 1 868 | – | |
| 2016 performance shares | 09/02/2016 | 09/02/2019 | – | 5 720 | – | – | – | – | |
| 2012 Phantom Cash Share Options | 02/07/2012 | 02/07/2015** | 252,01 | 5 000 | – | – | – | – | |
| 02/07/2016** | 252,01 | 5 000 | – | – | – | – | |||
| 02/07/2017** | 252,01 | 5 000 | – | – | – | – | |||
| 2013 Phantom Cash Share Options | 13/02/2013 | 13/02/2016 | 299,83 | 5 000 | – | – | – | – | |
| 13/02/2017 | 299,83 | 5 000 | – | – | – | – | |||
| 13/02/2018* | 299,83 | 10 000 | – | 5 000 | – | – | |||
| 2014 SARs | 28/02/2014 | 28/02/2017 | 254,45 | 6 067 | – | – | – | – | |
| 28/02/2018* | 254,45 | 6 067 | – | – | – | – | |||
| 28/02/2019 | 254,45 | 6 066 | – | – | – | – | |||
| 2015 SARs | 04/02/2015 | 04/02/2018* | 385,33 | 3 846 | – | 2 808 | – | – | |
| 04/02/2019 | 385,33 | 3 847 | – | – | – | – | |||
| 04/02/2020 | 385,33 | 3 847 | – | – | – | – | |||
| 2016 SARs | 09/02/2016 | 09/02/2019 | 291,71 | 7 623 | – | – | – | – | |
| 09/02/2020 | 291,71 | 7 623 | – | – | – | – | |||
| 09/02/2021 | 291,71 | 7 624 | – | – | – | – | |||
| 2016 SARs | 07/12/2016 | 07/12/2019 | 395,97 | 11 260 | – | – | – | – | |
| 07/12/2020 | 395,97 | 11 260 | – | – | – | – | |||
| 07/12/2021 | 395,97 | 11 260 | – | – | – | – | |||
| 2017 SARs | 11/12/2017 | 11/12/2020 | 414,45 | – | 15 276 | – | – | – | |
| 11/12/2021 | 414,45 | – | 15 277 | – | – | – | |||
| 11/12/2022 | 414,45 | – | 15 277 | – | – | – | |||
| Total | 142 336 | 45 830 | 7 808 | 1 868 | – |
| Name and awards | Closing number |
Face value at award ZAR |
Cash received ZAR |
Value of shares acquired ZAR |
Share price effect value of award ZAR |
Effective performance target |
Forfeited/ awarded during the year |
Closing fair value vesting ZAR |
|
| LC Mac Dougall | |||||||||
| 2016 deferred bonus shares | 650 | 257 381 | – | – | – | – | – | 167 089 | |
| 2016 company-matching shares | 650 | 257 381 | – | – | – | – | – | 167 089 | |
| 2016 bonus-matching shares | 650 | 257 381 | – | – | – | – | – | 167 089 | |
| 2016 performance shares | 8 160 | 2 788 109 | – | – | – | – | – | 172 583 | |
| 2016 SARs | 12 000 | 4 100 160 | – | – | – | – | – | 258 848 | |
| 12 000 | 4 100 160 | – | – | – | – | – | 372 600 | ||
| 12 000 | 4 100 160 | – | – | – | – | – | 447 000 | ||
| 2016 SARs | 10 946 | 4 334 288 | – | – | – | – | – | 226 363 | |
| 10 947 | 4 334 684 | – | – | – | – | – | 281 995 | ||
| 10 947 | 4 334 684 | – | – | – | – | – | 339 576 | ||
| 2017 SARs | 2 996 | 1 241 692 | – | – | – | – | – | 81 851 | |
| 2 997 | 1 242 107 | – | – | – | – | – | 96 533 | ||
| 2 997 | 1 242 107 | – | – | – | – | – | 105 165 | ||
| Total | 87 940 | 32 590 292 | – | – | – | – | – | 2 883 781 | |
| NP Doyle | |||||||||
| 2015 company-matching shares | 2 688 | 921 715 | – | – | – | – | – | 710 653 | |
| 2015 deferred bonus shares | 2 688 | 921 715 | – | – | – | – | – | 710 653 | |
| 2016 company-matching shares | 1 060 | 419 728 | – | – | – | – | – | 272 484 | |
| 2016 deferred bonus shares | 1 060 | 419 728 | – | – | – | – | – | 272 484 | |
| 2015 bonus-matching shares | 2 320 | 893 966 | – | – | – | – | – | 614 846 | |
| 2016 bonus-matching shares | 1 330 | 387 974 | – | – | – | – | – | 350 721 | |
| 2016 bonus-matching shares | 1 590 | 629 592 | – | – | – | – | – | 408 725 | |
| 2015 performance shares | 4 358 | 1 679 268 | – | – | – | – | – | 1 154 957 | |
| 2016 performance shares | 5 720 | 1 668 581 | – | – | – | – | – | 122 522 | |
| 2012 Phantom Cash Share Options | 5 000 | 1 260 050 | – | – | – | – | – | 65 050 | |
| 5 000 | 1 260 050 | – | – | – | – | – | 65 050 | ||
| 5 000 | 1 260 050 | – | – | – | – | – | 65 050 | ||
| 2013 Phantom Cash Share Options | 5 000 | 1 499 150 | – | – | – | – | – | – | |
| 5 000 | 1 499 150 | – | – | – | – | – | – | ||
| 5 000 | 1 499 150 | – | – | – | – | – | – | ||
| 2014 SARs | 6 067 | 1 543 748 | – | – | – | – | – | 180 069 | |
| 6 067 | 1 543 748 | – | – | – | – | – | 180 069 | ||
| 6 066 | 1 543 494 | – | – | – | – | – | 233 602 | ||
| 2015 SARs | 1 038 | 399 973 | – | – | – | – | – | 11 781 | |
| 3 847 | 1 482 365 | – | – | – | – | – | 44 587 | ||
| 3 847 | 1 482 365 | – | – | – | – | – | 45 010 | ||
| 2016 SARs | 7 623 | 2 223 705 | – | – | – | – | – | 226 327 | |
| 7 623 | 2 223 705 | – | – | – | – | – | 298 136 | ||
| 7 624 | 2 223 997 | – | – | – | – | – | 374 415 | ||
| 2016 SARs | 11 260 | 4 458 622 | – | – | – | – | – | 232 857 | |
| 11 260 | 4 458 622 | – | – | – | – | – | 290 058 | ||
| 11 260 | 4 458 622 | – | – | – | – | – | 349 285 | ||
| 2017 SARs | 15 276 | 6 331 138 | – | – | – | – | – | 417 340 | |
| 15 277 | 6 331 553 | – | – | – | – | – | 492 072 | ||
| 15 277 | 6 331 553 | – | – | – | – | – | 536 070 | ||
| Total | 182 226 | 63 257 077 | – | – | – | – | – | 8 724 873 |
| * | Vesting date extended as a consequence of the voluntary closed period. |
| ** | Lapsing of shares extended as a consequence of closed period. Shares should have been exercised by 02/07/2018. |
Interests of directors and prescribed officers in BBBEE schemes
No executive director or prescribed officer, other than PD Sithole who was granted 7 000 Tiger Brands and 5 950 Adcock Ingram Shares on 31 January 2013. In addition, Y Maharaj, will qualify to participate in the company’s BMT I scheme when he will be granted 20 000 shares in Tiger Brands Limited, once the closed period has been lifted.
PD Sithole was also granted 9 202 Tiger Brands shares in terms of the BMT II scheme on 30 September 2017. This grant is subject to a three year retention period which expires on 30 September 2020.
Non-executive directors’ remuneration 2018
The non-executive director remuneration paid during the year under review (as approved by shareholders on 20 February 2018) and the total comparative figure for 2017 are disclosed below, excluding VAT:
| Committee | MO Ajukwu | SL Botha3 | MJ Bowman | GA Klintworth1 | M Makanjee | E Mashilwane | |
| Board fees | 890 074 | 93 929 | 386 989 | 229 000 | 386 989 | 386 989 | |
|---|---|---|---|---|---|---|---|
| Audit committee fees | – | – | – | – | – | 168 896 | |
| Investment committee fees | – | – | 25 552 | – | – | – | |
| Remuneration and nomination committee fees | – | 23 548 | 214 717 | – | 97 017 | – | |
| Nomination committee fees | – | – | – | – | – | – | |
| Social, ethics and transformation committee fees | – | – | – | – | 177 186 | – | |
| Risk committee fees | 318 258 | – | – | – | – | – | |
| Extraordinary fees | – | – | – | – | – | – | |
| Ad hoc work/meetings | – | – | 20 127 | – | 22 093 | – | |
| Total FY18 | 1 208 332 | 117 477 | 647 384 | 229 000 | 683 284 | 555 884 | |
| Total FY17 | 812 387 | 577 780 | 477 468 | – | 612 393 | 360 163 |
| Committee | Dr KD Mokhele | RD Nisbet4 | MP Nyama | YGH Suleman | BS Tshabalala2 | |
| Board fees | 1 797 170 | 386 989 | 386 989 | 386 989 | 386 989 | |
|---|---|---|---|---|---|---|
| Audit committee fees | – | 294 110 | – | 168 896 | – | |
| Investment committee fees | – | 25 552 | – | 25 552 | – | |
| Remuneration and nomination committee fees | – | – | 97 017 | – | – | |
| Nomination committee fees | – | – | – | – | – | |
| Social, ethics and transformation committee fees | – | – | 88 593 | – | – | |
| Risk committee fees | – | 138 374 | – | 272 679 | 138 374 | |
| Extraordinary fees | – | – | – | – | – | |
| Ad hoc work/meetings | 8 334 | 27 989 | – | 22 093 | – | |
| Total FY18 | 1 805 504 | 873 012 | 572 598 | 876 207 | 525 362 | |
| Total FY17 | 1 280 705 | 819 716 | 553 695 | 745 002 | 93 929 |
| 1 | Appointed 16 August 2018. |
| 2 | Resigned 15 August 2018. |
| 3 | Resigned 24 November 2017. |
| 4 | Resigned 7 September 2018. |
Non-executive directors’ remuneration 2017
The non-executive director remuneration paid for the year ended 30 September 2017 is disclosed below, excluding VAT:
| MO Ajukwu | SL Botha | MJ Bowman | K Hedderwick1 | M Makanjee | E Mashilwane2 | Dr KD Mokhele6 | ||
| Board fees | 612 707 | 368 491 | 368 491 | 90 316 | 368 491 | 278 175 | 1 053 045 | |
| Carozzí board meeting | – | – | – | – | – | – | – | |
| Audit committee fees | – | – | – | – | – | 81 988 | 71 823 | |
| Investment committee fees | – | – | 41 805 | – | – | – | 11 340 | |
| Remuneration committee fees | – | 201 729 | – | – | 47 096 | – | – | |
| Nominations committee fees | – | 7 560 | – | – | 7 560 | – | – | |
| Social, ethics and transformation committee fees | – | – | – | – | 164 046 | – | – | |
| Risk committee fees | 199 680 | – | 67 172 | – | – | – | 96 617 | |
| Extraordinary fees | – | – | – | – | – | – | – | |
| Ad hoc work/meetings* | – | – | – | – | 25 200 | – | 47 880 | |
| TOTAL FY17 | 812 387 | 577 780 | 477 468 | 90 316 | 612 393 | 360 163 | 1 280 705 |
| BL Sibiya3 | RD Nisbet | MP Nyama | AC Parker4 | YGH Suleman | BS Tshabalala5 | ||
| Board fees | 658 948 | 368 491 | 368 491 | 838 858 | 368 491 | 93 929 | |
| Carozzí board meeting | – | – | – | 218 010 | – | – | |
| Audit committee fees | – | 280 052 | – | – | 153 811 | – | |
| Investment committee fees | – | 58 815 | – | – | 41 805 | – | |
| Remuneration committee fees | – | – | 95 621 | – | 48 526 | – | |
| Nominations committee fees | – | – | 7 560 | – | – | – | |
| Social, ethics and transformation committee fees | – | – | 82 022 | – | – | – | |
| Risk committee fees | – | 112 357 | – | – | 132 369 | – | |
| Extraordinary fees | – | – | – | – | – | – | |
| Ad hoc work/meetings* | – | – | – | 22 680 | – | – | |
| TOTAL FY17 | 658 948 | 819 716 | 553 695 | 1 079 548 | 745 002 | 93 929 |
| 1 | Appointed on 1 December 2016 and resigned on 14 February 2017. |
| 2 | Appointed on 1 December 2016. |
| 3 | Resigned on 30 June 2017. |
| 4 | Resigned as chairman on 21 February 2017. |
| 5 | Appointed on 26 May 2017. |
| 6 | Appointed as chairman on 21 February 2017. |
| * | Paid for special meetings attended for committee of the board. |
Non-executive directors’ remuneration 2019
The following table reflects proposed fees from 1 March 2019, excluding VAT, subject to the approval of shareholders at the AGM on 19 February 2019:
| Forum | Capacity | Current rate effective March 2018 |
Proposed rate resident board members – effective March 2019 |
Proposed fees to be paid to non-resident board members – effective March 2019 |
|||||
| Main board | Chairman | 1 849 515 | 1 941 990 | * | |||||
|---|---|---|---|---|---|---|---|---|---|
| Member | 398 260 | 418 173 | 961 798 | ||||||
| Audit | Chairman | 302 676 | 326 890 | * | |||||
| Member | 173 815 | 186 851 | * | ||||||
| Remuneration and nominations | Chairman | 220 971 | 229 810 | * | |||||
| Member | 99 842 | 107 331 | * | ||||||
| Risk | Chairman | 280 621 | 290 443 | * | |||||
| Member | 142 404 | 148 100 | 340 629 | ||||||
| Social, ethics and transformation | Chairman | 182 347 | 195 111 | * | |||||
| Member | 91 173 | 98 467 | * | ||||||
| Hourly fees | 4 167 | 4 396 | 10 111 | ||||||
| Extraordinary meetings | 20 951 | 22 103 | 50 837 |
* Not applicable.
Non-binding advisory vote
Shareholders are requested to cast two separate non-binding votes on the remuneration policy and implementation report in parts 2 and 3 of this report.