




 44 / 276

PERFORMANCE REVIEW
42
Tiger Brands Limited Integrated Annual Report
2014
Divisional review
continued
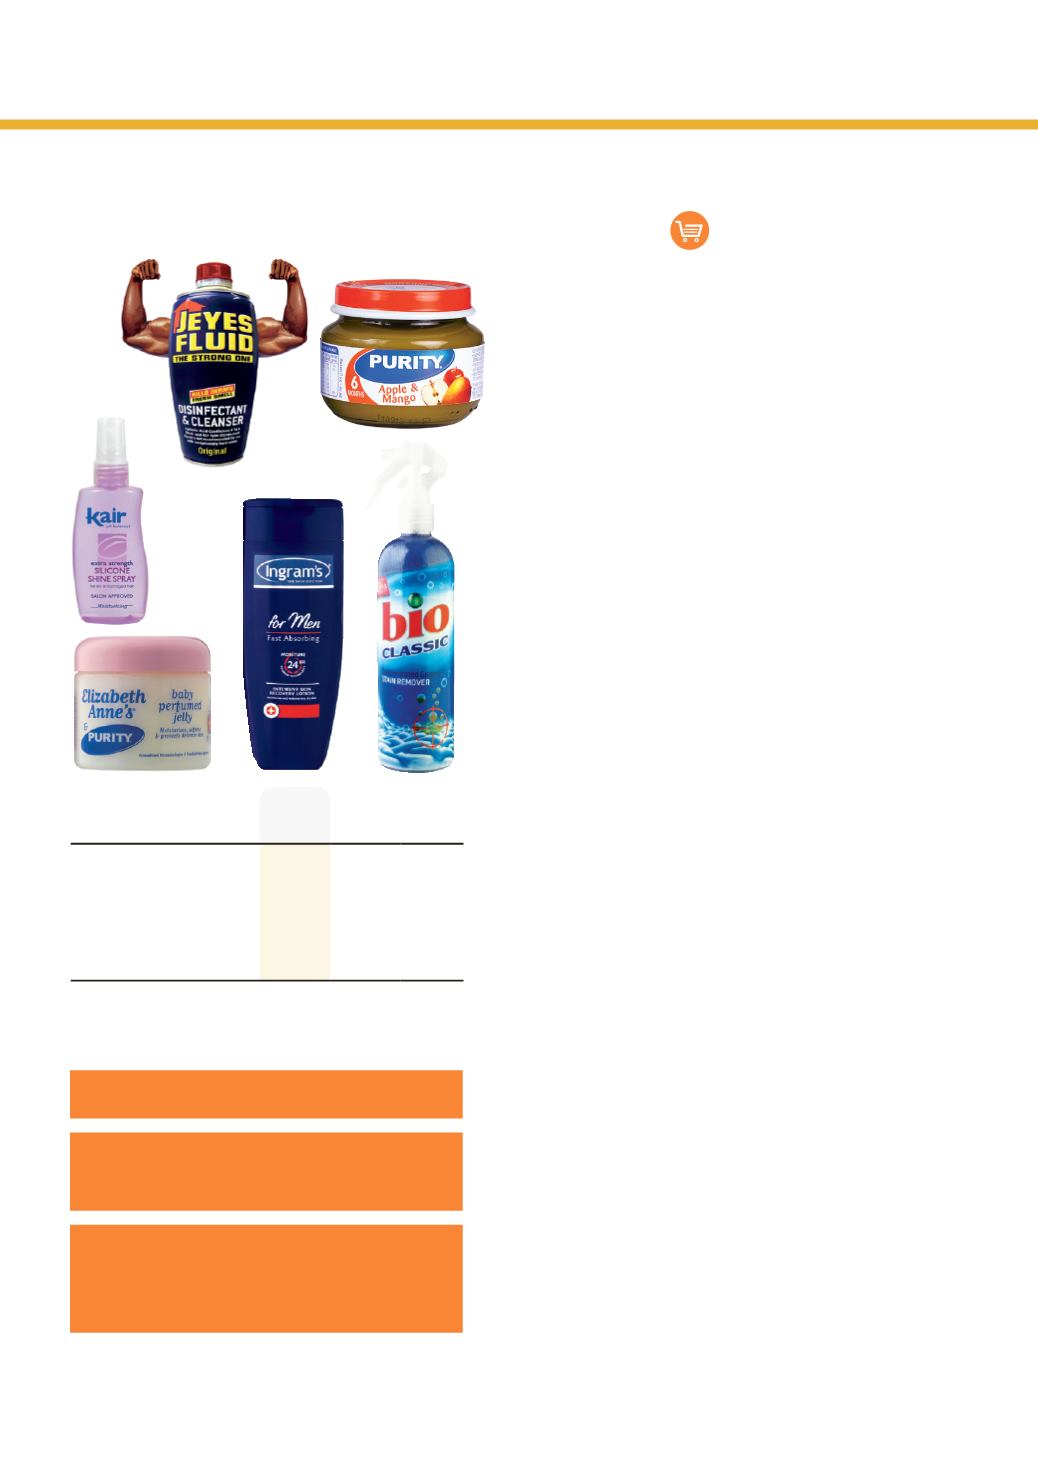
Home, Personal Care and Baby (HPCB)
The period under review proved to be
challenging for the HPCB business. It delivered
modest revenue growth and compressed
operating profit on the back of market
contraction in several categories in which the
business competes. The HPCB categories
continue to witness significant levels of brand
investment, high innovation rates and
aggressive pricing.
Home Care category growth was driven by
the Pest segment. However, aggressive
competitor pricing led to high levels of
discounting in the Pest and Fabric Care
segments. This, coupled with input cost inflation
which was not fully recovered in pricing,
resulted in margin compression.
The Personal Care performance was driven
by reasonable revenue growth in Body Care.
However, margins also contracted due to input
cost inflation not fully recovered in pricing, with
volume declines experienced in the highly
competitive Hair Care and Fragrance
segments.
Within Baby Care, both the Nutrition and
Well-being segments delivered satisfactory
revenue growth. The Baby Care category has
slowed as a result of market contraction in
jarred baby foods and consumers down-
trading to lower priced alternatives. Both Baby
Cereals and Porridges have seen good
volume growth.
Salient features
Challenging trading environment
Significantly increased level of
marketing investment
Input cost inflation which was not
fully recovered in pricing, resulted in
margin compression
(R’million)
2014
2013
%
change
Turnover (Rm)
1 960,2
1 877,0 4%
Operating income before
abnormal items (Rm)
398,5
439,3 (9%)
Operating margin (%)
20,3%
23,4%